


As par-plus loans begin to drift lower, new repricing candidates prove no easier to find

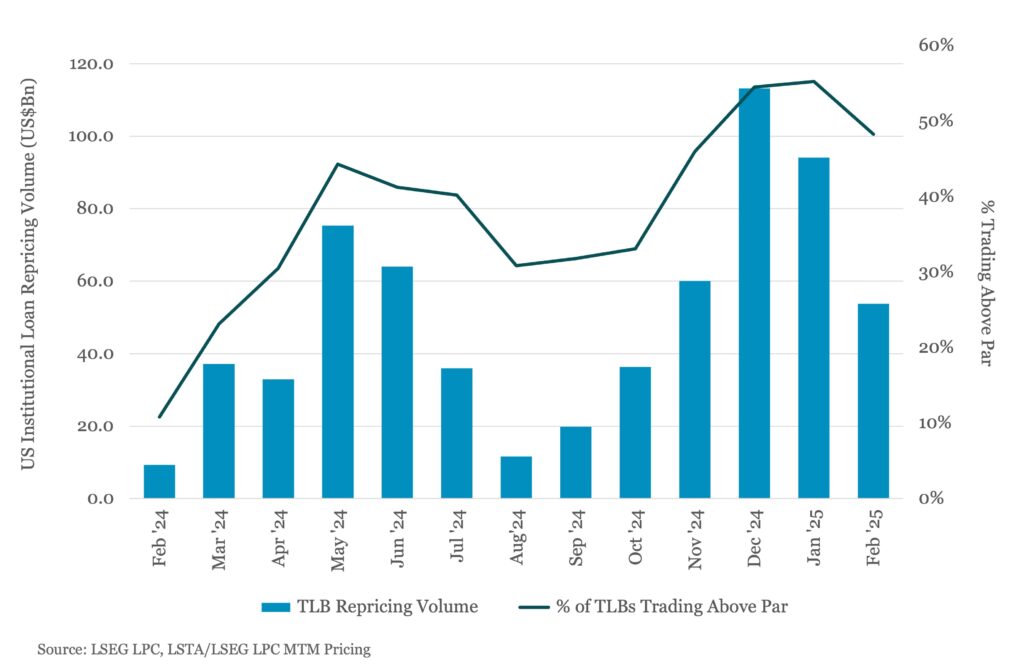
Regardless of where one points the blame – a slight downshift in technicals, cracks in broader market conditions, or the self-fulfilling dynamic that the vast majority of issuers that could reprice have already done so – the share of institutional loans trading above par has begun to move noticeably lower. Par-plus loans now account for 48% of the secondary market, still a commendable share although trending below 50% for the first time since November. And term loan B repricings have begun to slow in parallel, with February issuance trending nearly 50% lower since January, at US$54bn versus US$94bn, respectively. There’s still one week left in February for a final push, although one can’t help but ask: Is the Great Repricing Wave beginning to finally turn? Or simply taking a much needed breather? Two related themes seem fairly certain: (1) Straight refinancings are beginning to take prominence over mark-to-market repricings, as repricings now account for nearly 50% of total institutional loan refinancings versus about 75% in January; (2) Investors are still holding the floor for institutional loan pricing at S+175bp, at least for now.




Latest news

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Reading the Board
The story changes depending on which numbers you’re counting.
Private Credit Defaults 101: Different Numbers, Different Stories
In Season 2 of Billions, Bobby Axelrod takes his lawyer Orrin Bach to an empty Yonkers racetrack in the dead of night.