


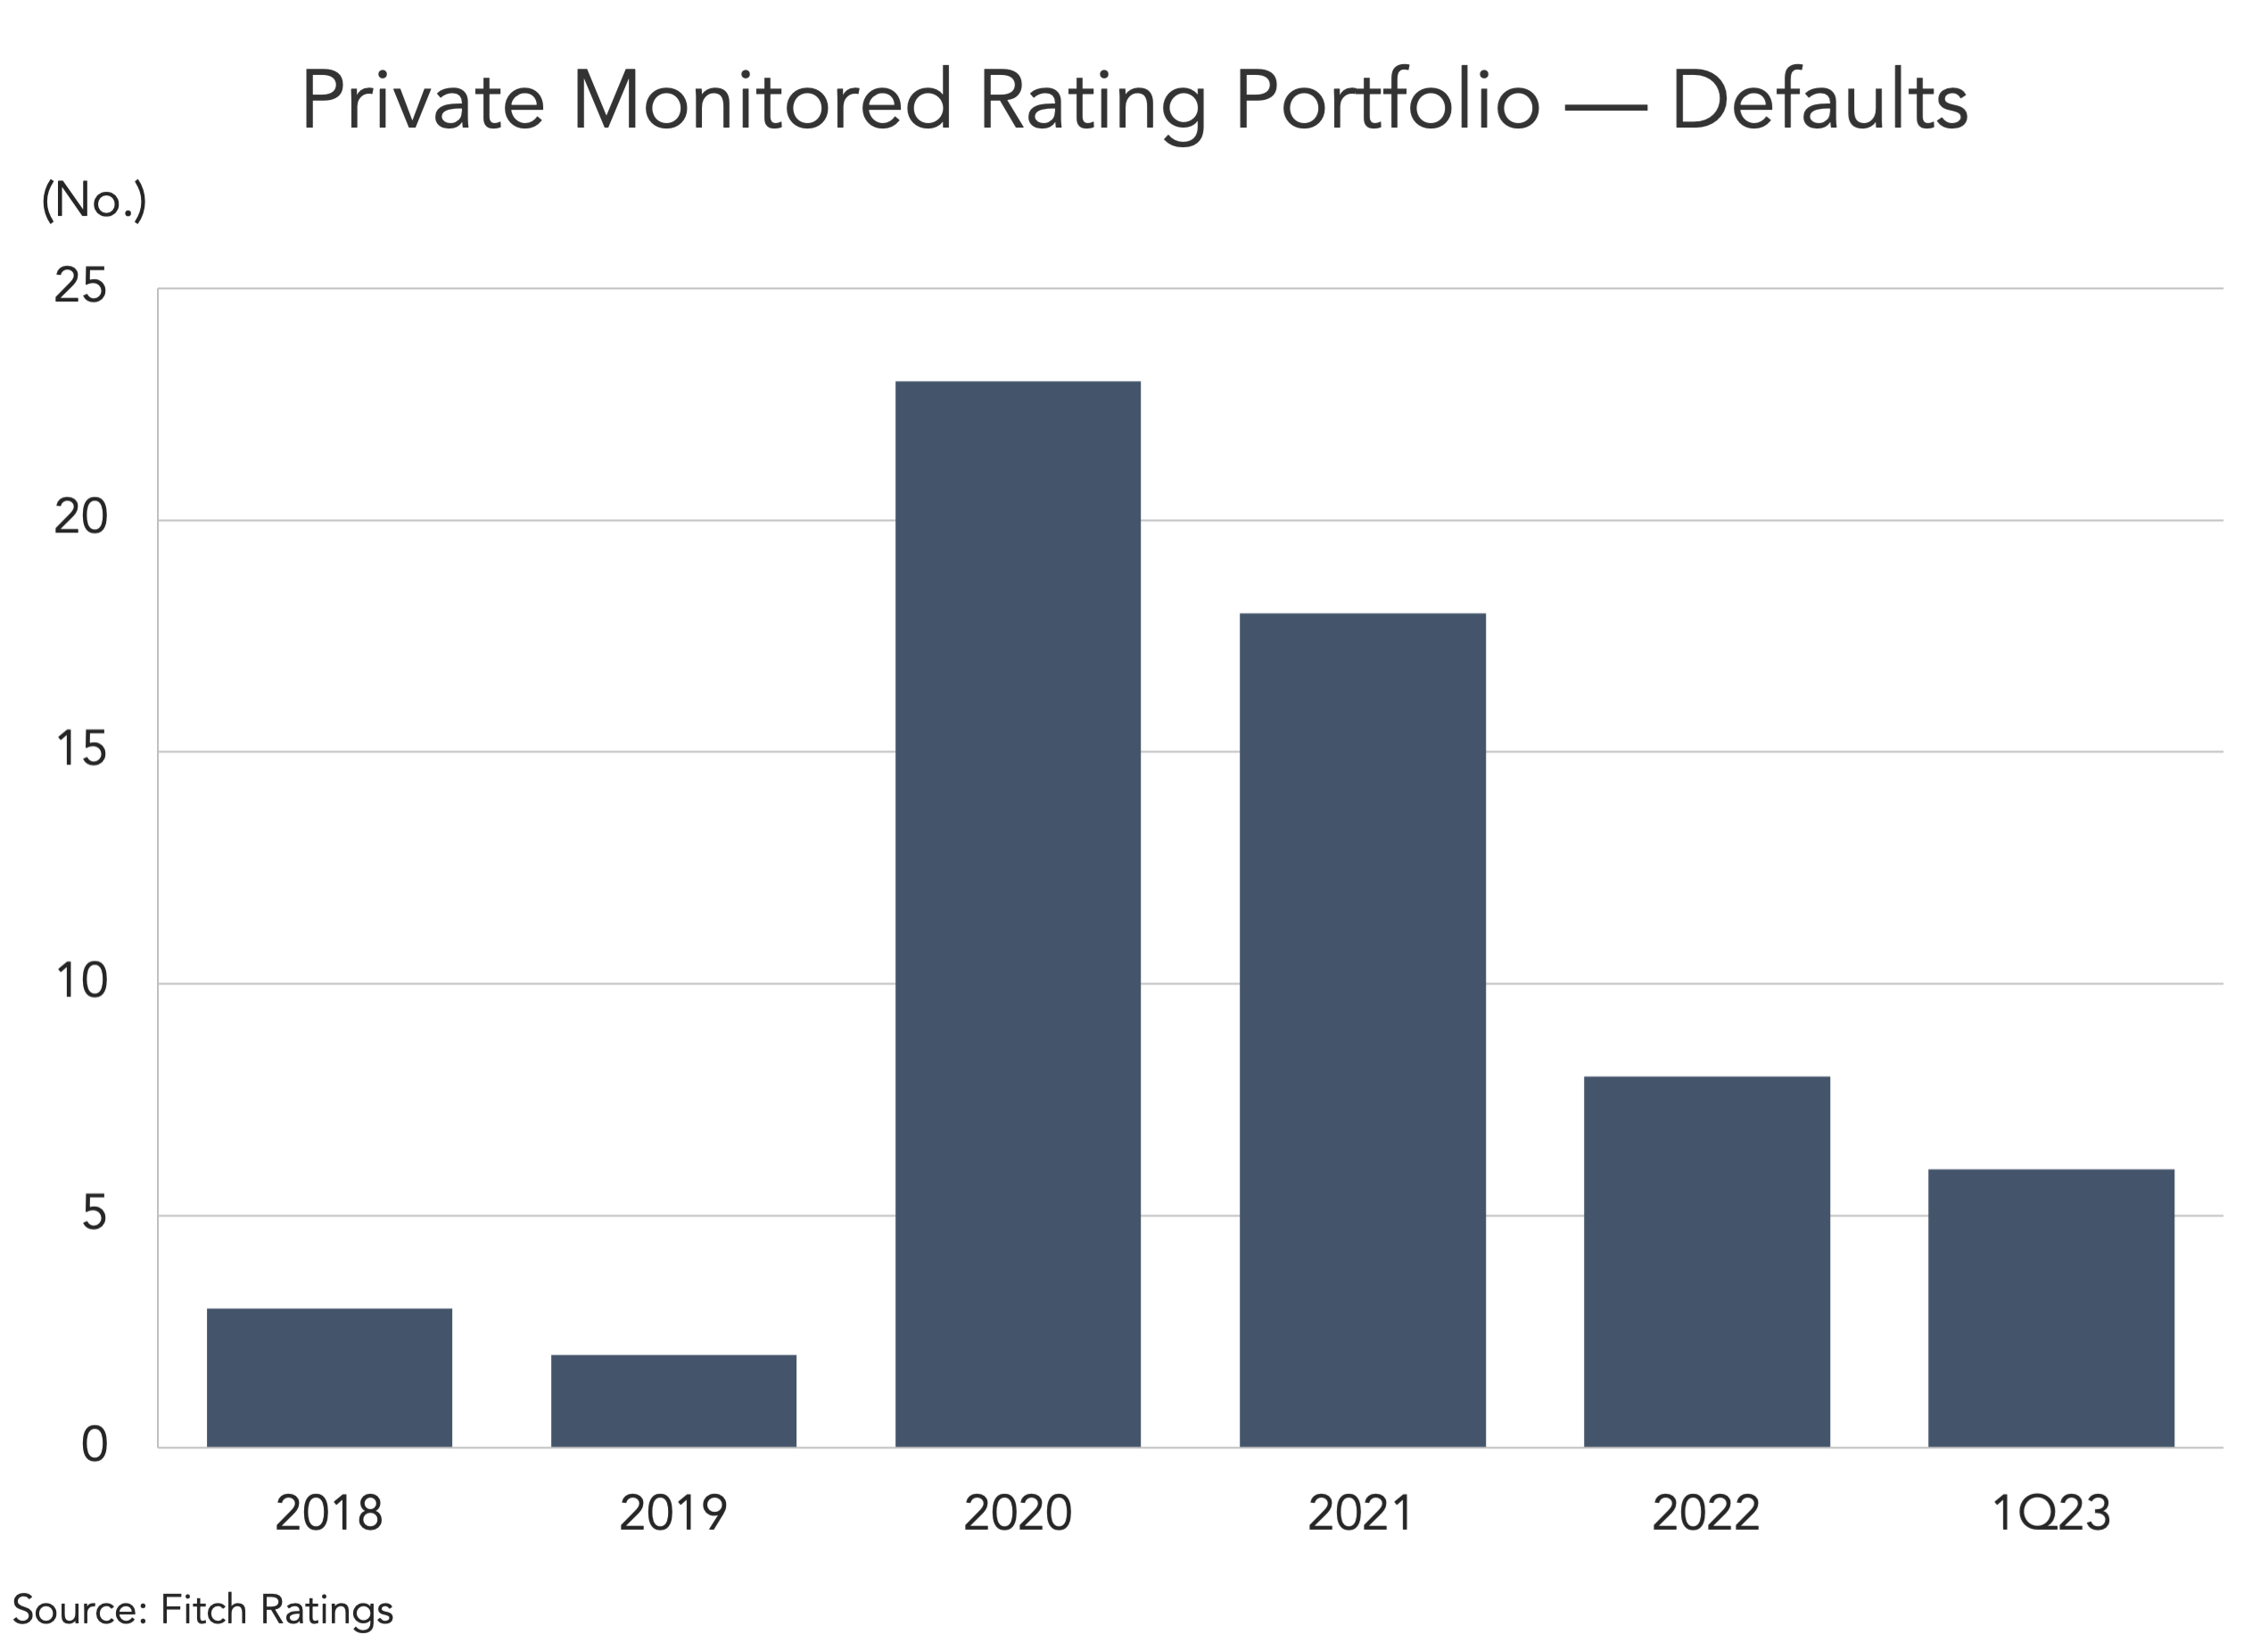
Fitch recorded eight defaults in our Private Monitored Rating (PMR) portfolio in 2022, down from the pandemic-affected years of 2020 and 2021 when we recorded 23 and 18 respectively. YTD defaults through June 2023 total seven, one short of the total in 2022 and ahead of full-year 2018 and 2019 totals.
Fitch expects defaults in our PMR portfolio to remain elevated through 2023 and into 2024 as companies with compromised business models buckle under the weight of high interest rates and weakening demand. Elevated interest expense could result in otherwise healthy companies seeking concessions from lenders on cash payments, which could further pressure defaults.
CTA button: Download Report
(Past performance is no guarantee of future results.)



Latest news

PIK Your Next Adventure
Every amended PIK loan hits the same crossroad. Not everyone ends up at the same destination.

Top 50 BDCs Accounted for 75% of Nonaccrual Loan Cost in Q2’26
The 50 largest BDCs, on the basis of total debt investments as of the second quarter of 2026, accounted for 75% of the total aggregate reported value of nonaccrual debt at cost and fair value.
Private Credit Defaults 101: Beyond the Noise
Like any good school year, this series went by fast. But unlike the end of the year, we’re not out for the summer.