


Download PitchBook’s Report here.
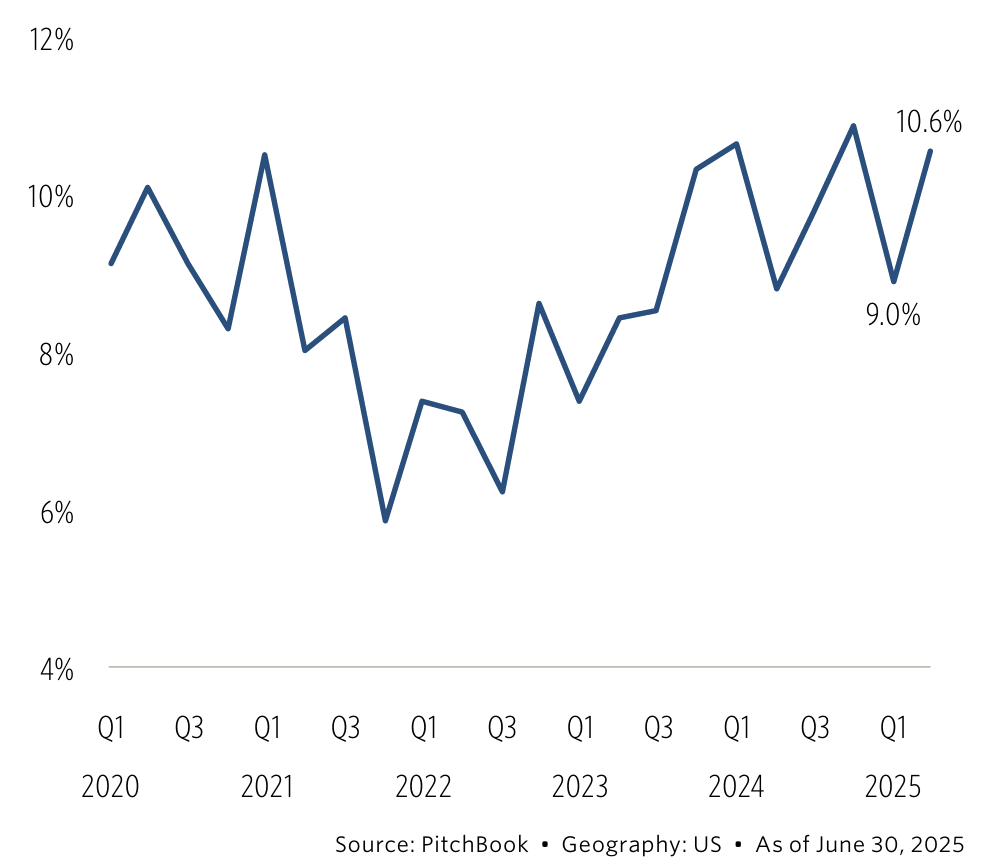
Carve-out transactions are running at 10.6% of all buyout deals in 2025, which is comfortably above the five-year average of 8.7% and last year’s 10.1%. Still, we are hearing that sellers are opting to wait out the current volatility caused by tariff-driven supply chain gyrations rather than divest into volatility. Examples include companies that are unable to economically provision process inputs or finished goods, and are waiting for clarity on US tariff policy and broader trading relationships before green-lighting spinouts—which could set the stage for a stronger second half as public-equity indexes hover near their recent highs and valuation confidence returns.
(Past performance is no guarantee of future results.)


Latest news
US leveraged loan primary market stalls in 4Q26
Primary market activity in the US leveraged loan market has slowed sharply in the fourth quarter. Just $34.9b of new…

Direct lending M&A declines QoQ and YoY except in upper middle market
M&A activity declined 12% in the third quarter of 2026 to 296 deals, from 336 recorded in the second quarter.