



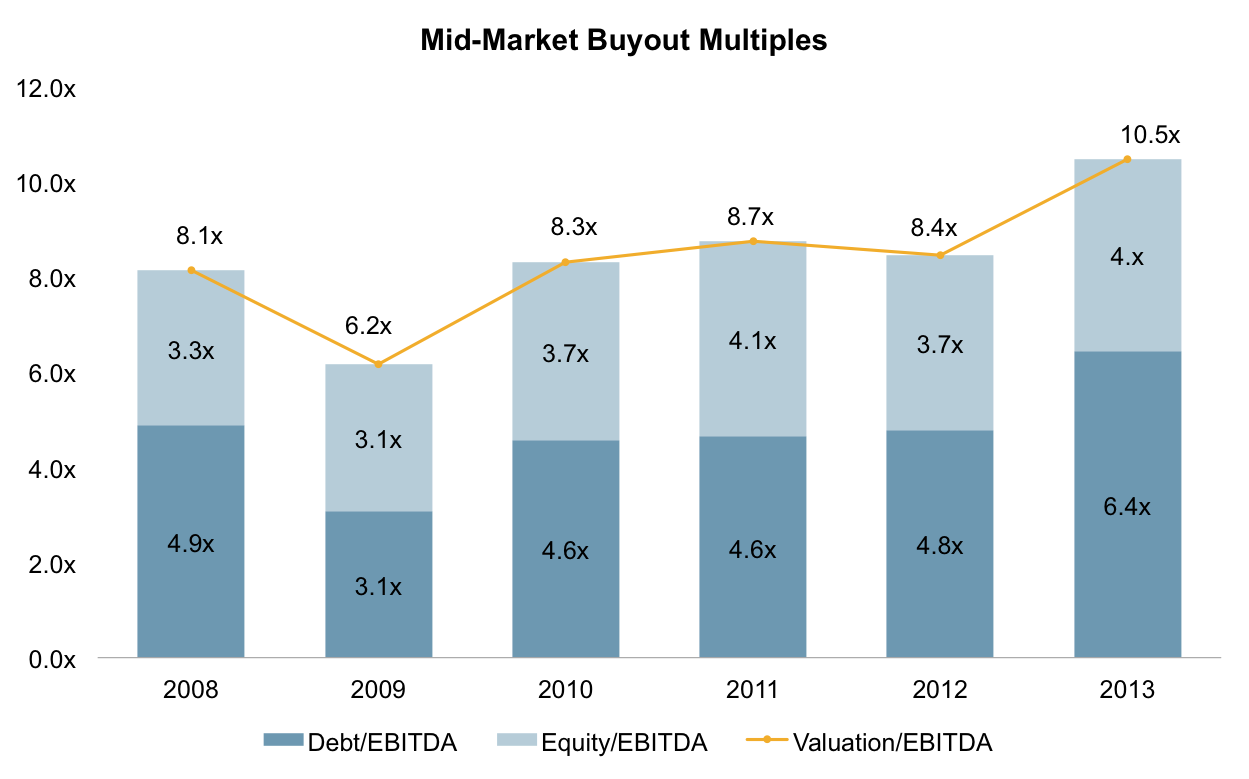
At ACG Intergrowth last week I spent a fair amount of time talking with private equity deal guys (and one gal…another topic) about the current market. The clearest trend everyone could agree on, and one that nobody was particularly excited about, was the increase in company valuation multiples over the last 12 to 18 months. Consensus put EBITDA multiples going up by about 1x to 2x over this short time frame, a fact verified by the data we have captured on middle-market transactions (see above).
There are several drivers behind this multiple expansion and it is hard to quantify the impact of each individual one but the three big ones are as follows. There continues to be increased deal competition for quality deals from both strategic and PE firms, both of which have plenty of money. Leverage for transactions is accessible and cheap as it has almost ever been, allowing firms to put in the same amount of equity as before and just finance the multiple increases. Quality companies have now shown three years of positive financials, essentially wiping the Great Recessions from their books.
The strategies and tactics being used by PE firms as result ranged from nothing different to only buying companies that could be expected to still hit return goals but in a lower multiple environment. Whatever the response is, it is clear that valuation multiple increases are going to continue providing a headache for the foreseeable future.




Private Credit Defaults 101: Back to School
As Labor Day approaches, the unofficial end of summer is upon us. But, before we get too sad, there is also the familiar back-to-school energy.