


Private Debt Intelligence – 9/11/2017

Private Debt Fund Managers Gauge Investor Appetite
Chart
Download Data
[wpdm_package id=’14135′]
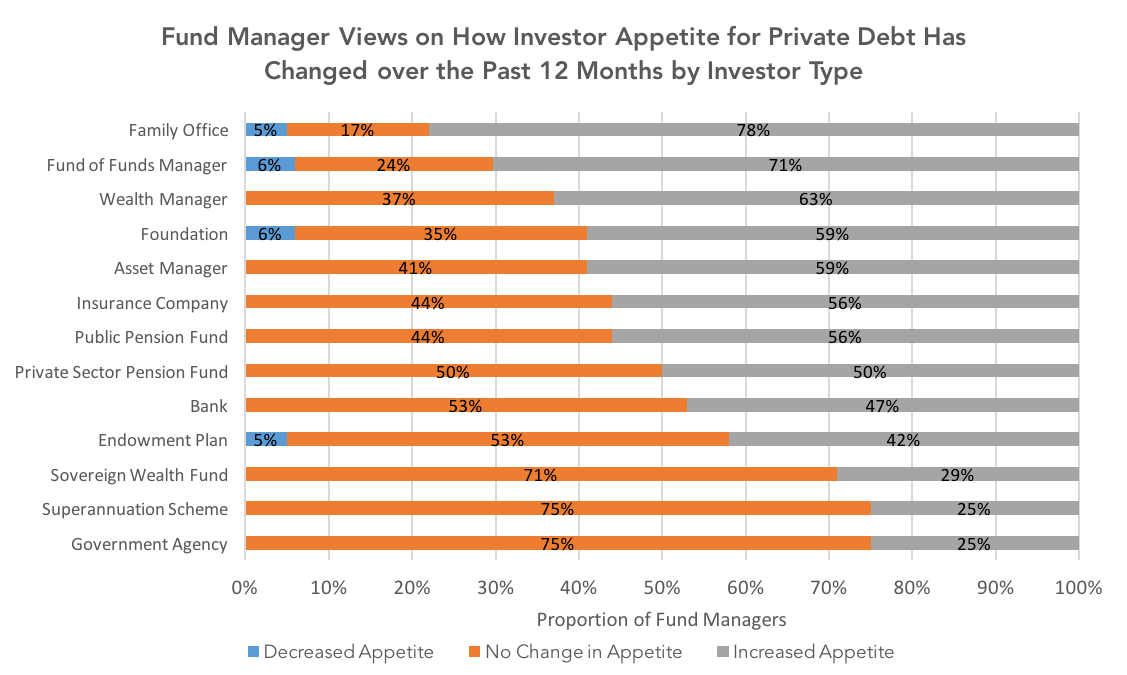
Preqin’s mid-year survey of private debt fund managers found that the vast majority have seen investors become even more keen to participate in the asset class over the past 12 months. Ninety percent of surveyed firms reported that they had seen investor appetite increase in the 12 months to June 2017, and almost a third (32%) said it had increased significantly. The remaining 10% of firms said they had seen no change in appetite, and no fund managers reported seeing an overall decrease in investor interest.
However, there is significant variation in the changing levels of appetite firms reported seeing from different types of institution. More than three-quarters (78%) have seen an increase in appetite from family offices, while just 5% have seen interest decline from these investors. This is in line with recent trends in the industry, which have seen family offices become one of the fastest-growing segments of the investor universe. Similarly, wealth managers and funds of funds were some of the other investor types most cited by managers as having increased their interest in private debt in the past 12 months.
Some institutions have been slower to increase their appetite levels in the past year. Twenty-nine percent of fund managers have seen interest from sovereign wealth funds increase, while the remainder have seen no change. This is perhaps unsurprising: Preqin found earlier in the year that just 39% of sovereign wealth funds currently have an allocation to real estate, and this proportion seems to be growing slowly.
An even smaller proportion of fund managers (25%) have seen growth in appetite from superannuation schemes. This is perhaps because most superannuation schemes are based in Australia, and the private debt industry in the region remains very small. However, it is worth noting that no investor type has seen a net decrease in appetite over the past 12 months, and the momentum remains very much towards institutions becoming more active in the private debt sphere.




Latest news
The Recovery Shot
Trouble off the tee doesn’t always translate to trouble on the scorecard.

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Private Credit Defaults 101: Scrambling for Par
Seve Ballesteros won four majors in the 1980s despite being, by his own admission, one of the wildest drivers of the golf ball on tour.