


Click here to download report.
How Does the Change in Rate Outlook Affect Middle-Market Borrowers?
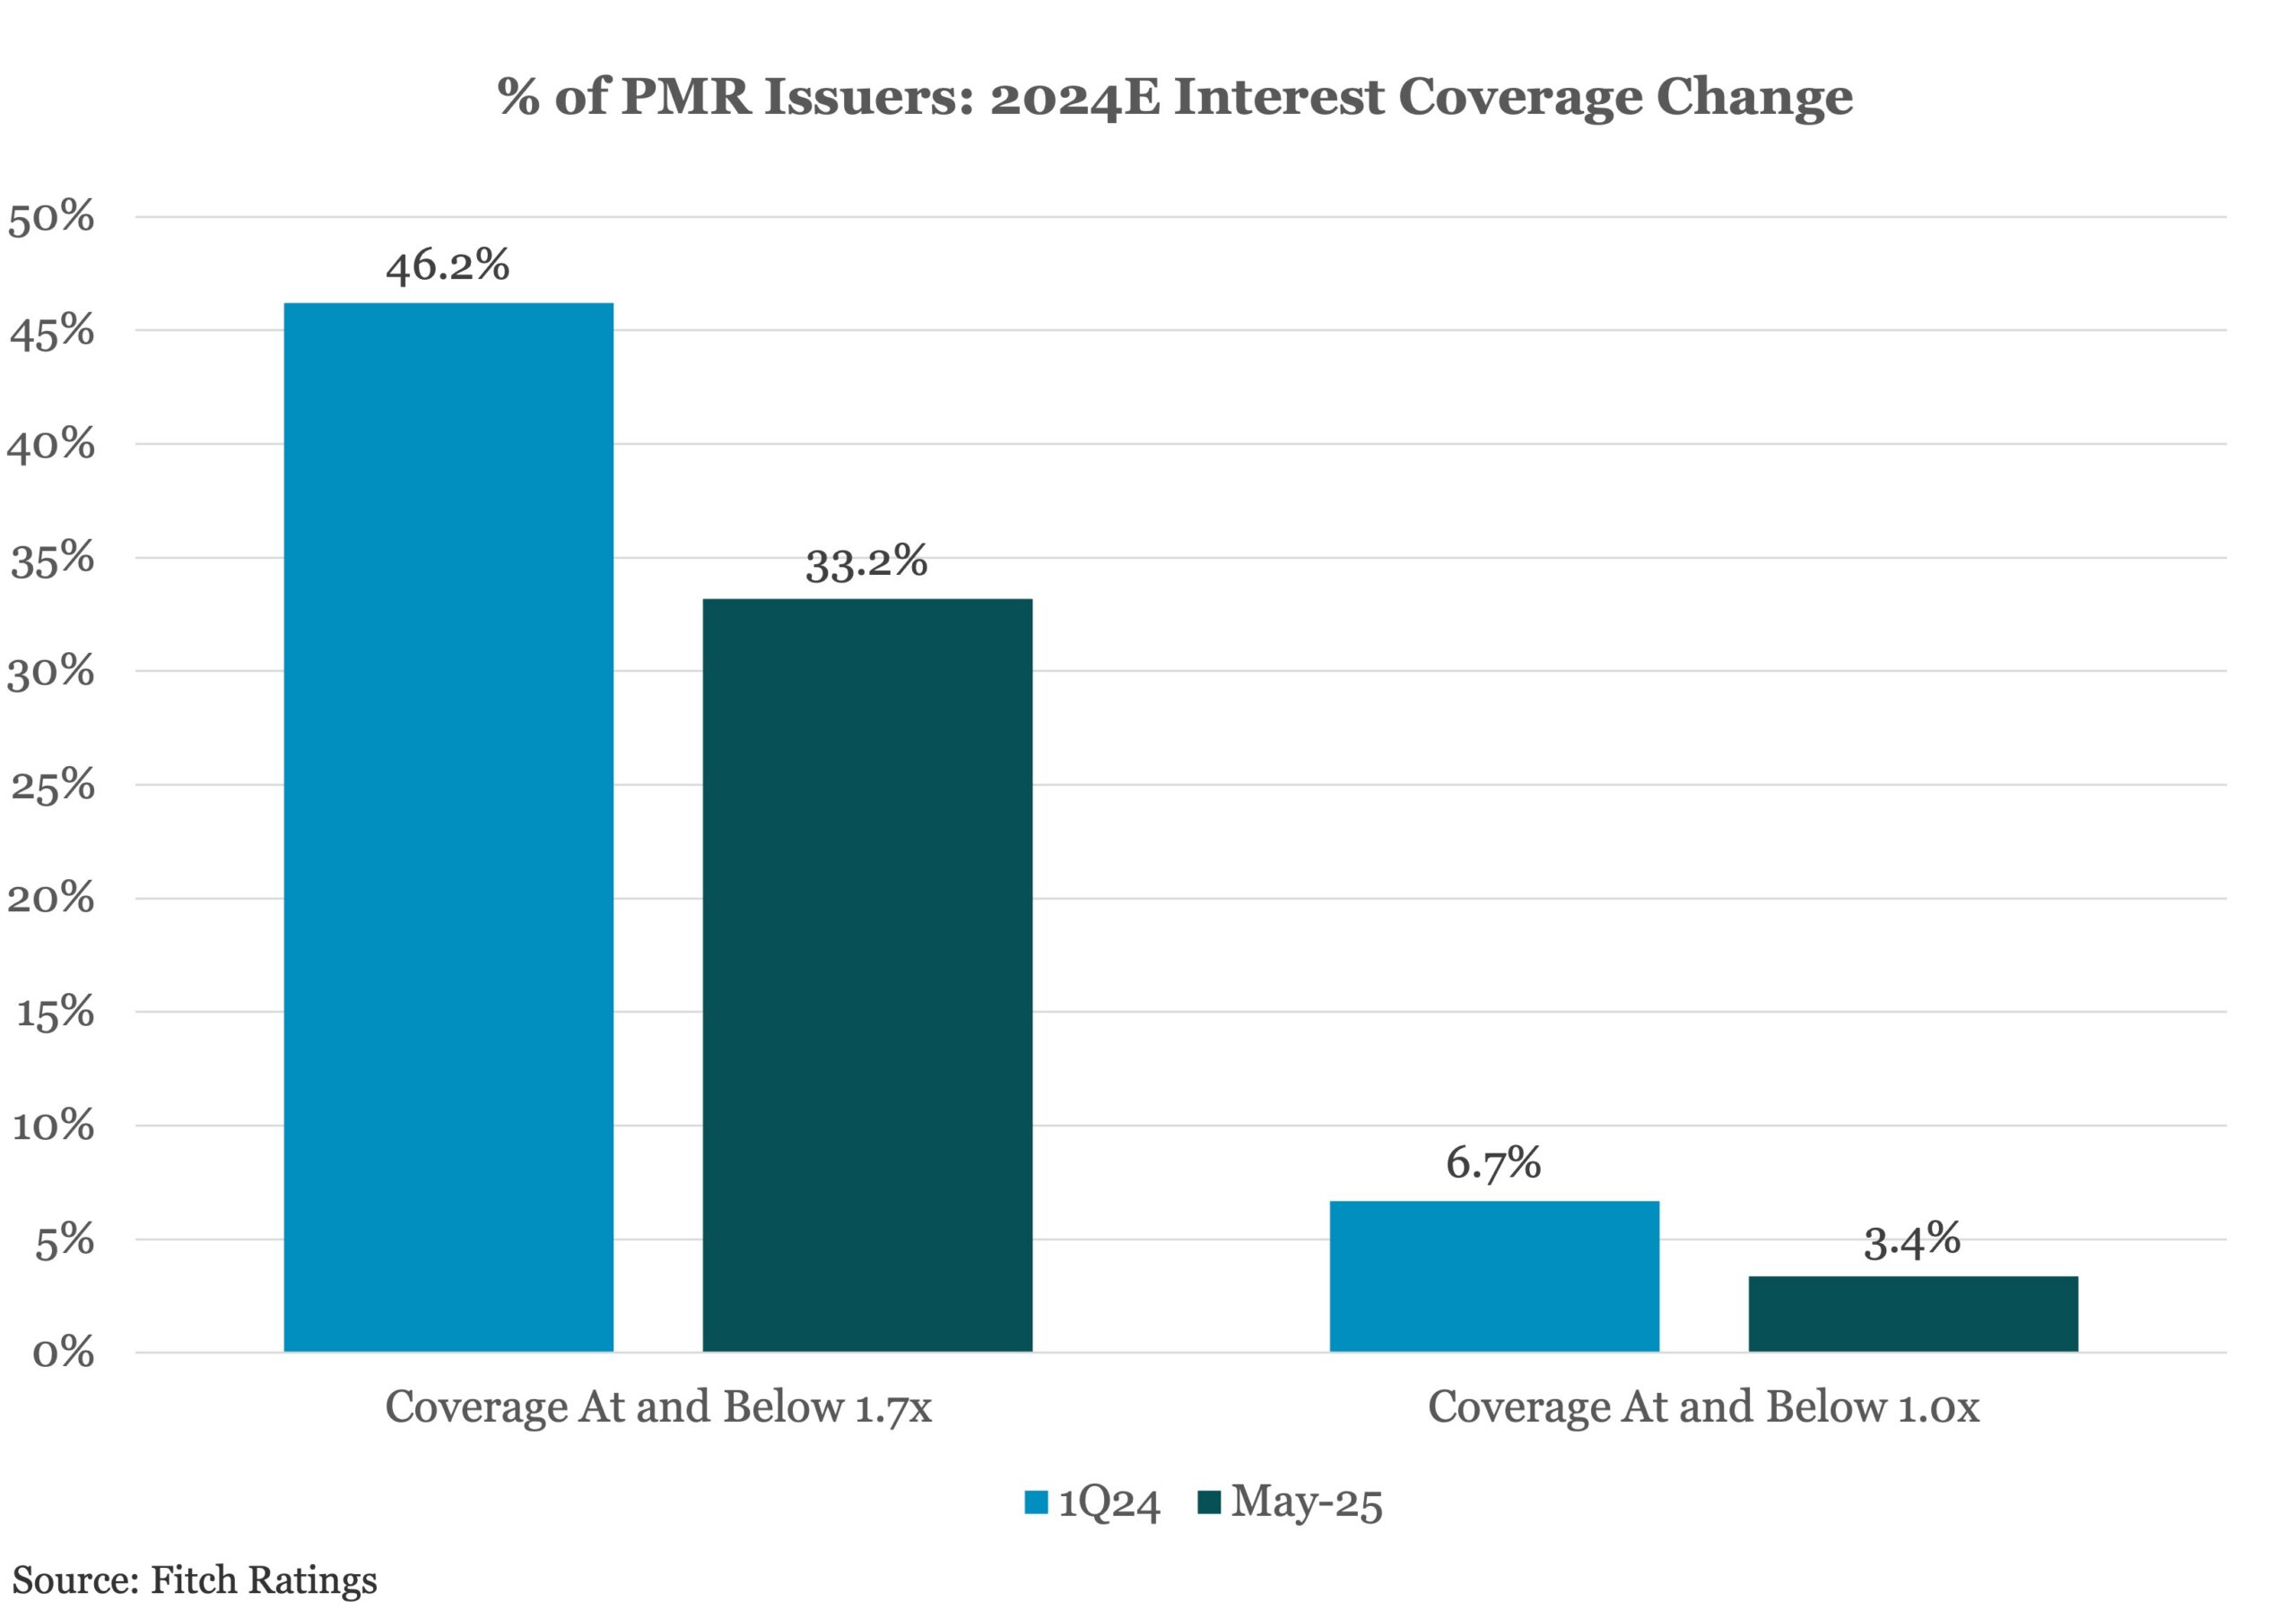
Despite concerning growth in the number of issuers with coverage at or below 1x, the median issuer’s metrics have remained relatively stable. Approximately 48% of all issuers are estimated to have 2024E interest coverage at or below 1.7x, just slightly up from 46% in 1Q24.
The deterioration in interest coverage metrics has translated into an elevated TTM default rate of 7.8% for March 2025. We expect the privately monitored rating (PMR) default rate to remain elevated throughout 2025 given the revised interest rate outlook and PMR issuers’ limited abilities to withstand economic pressures due to their smaller scale and limited diversification.
Without meaningful macroeconomic relief or interest rate reductions, the 17% of issuers already estimated to have 2024E interest coverage levels of 1.0x or below would be at significant risk of experiencing liquidity issues potentially leading to default.
Contact: Brad Hamner
Brad.Hamner@fitchratings.com




Latest news
The Recovery Shot
Trouble off the tee doesn’t always translate to trouble on the scorecard.

Q2'26 BDC analysis shows additional 184 bps of nonaccruals at cost
In a universe of 173 business development companies, or BDCs, Octus identified a total of $9.5 billion of debt (at cost) in nonaccrual status reported in the second quarter of 2026, a slight decline of 5% from $10 billion in the first quarter of 2026.
Private Credit Defaults 101: Scrambling for Par
Seve Ballesteros won four majors in the 1980s despite being, by his own admission, one of the wildest drivers of the golf ball on tour.