


Click here to learn more.
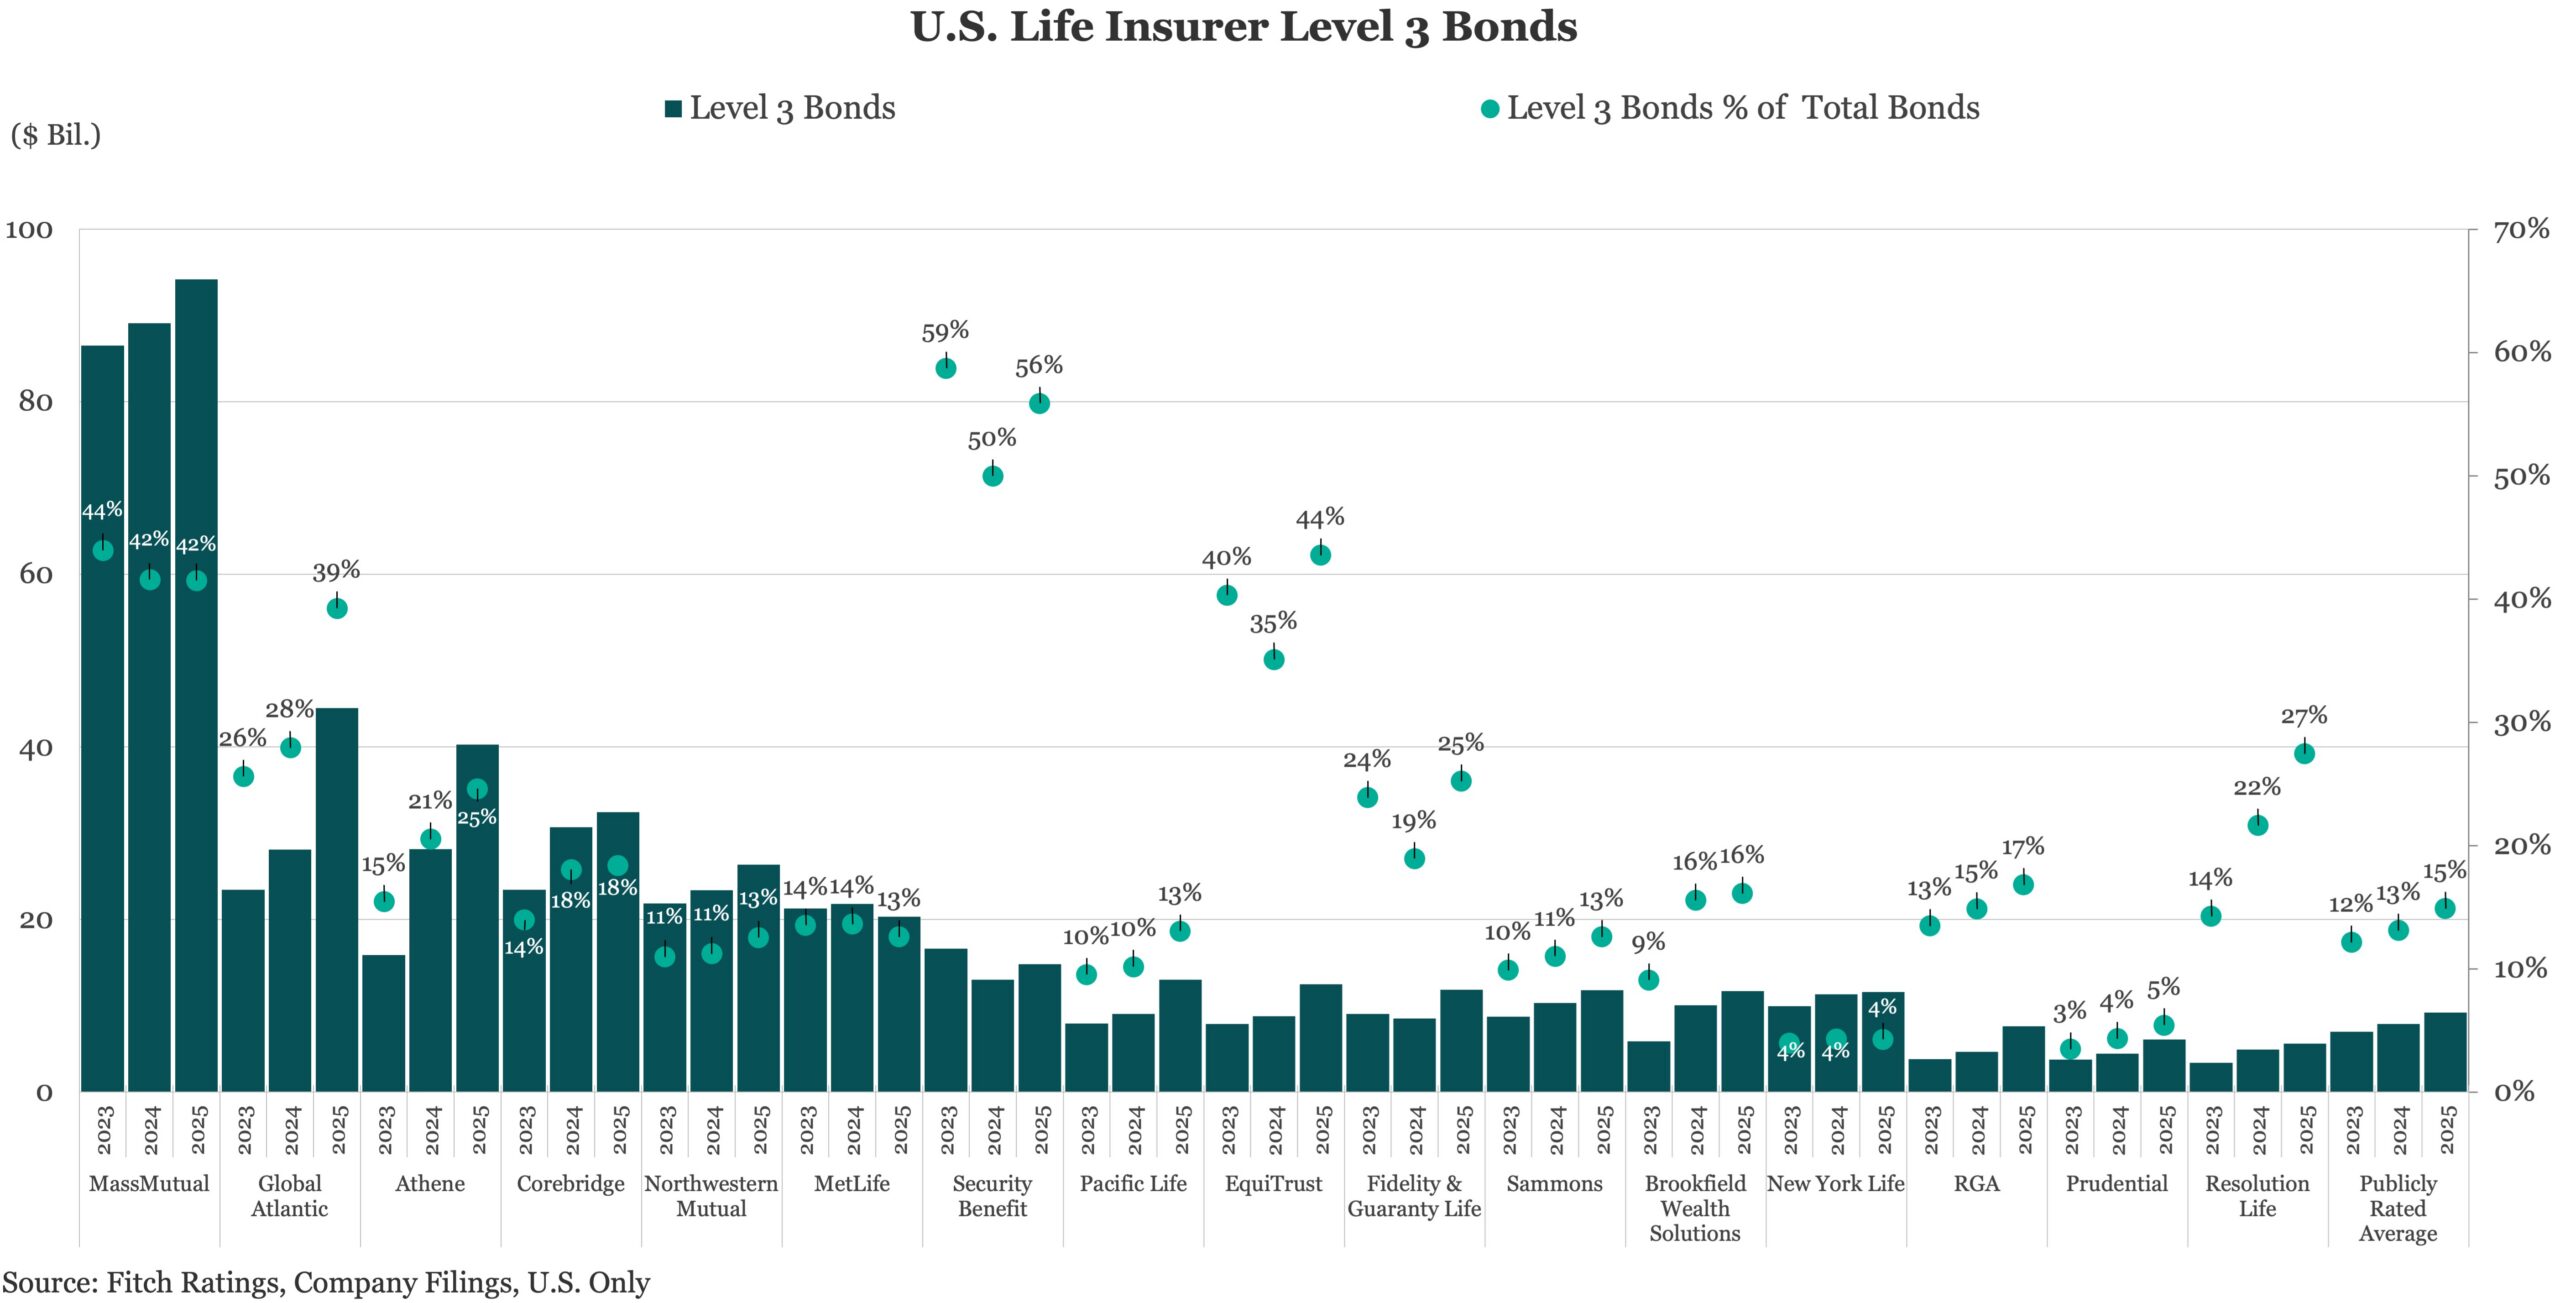
In recent years, bank and insurance regulators have pushed for more private credit disclosure in response to emerging risks. For life insurers, potential risks include meaningful investment exposure, capital adequacy for privately rated investments and potential conflicts of interest associated with growing ties with Alt IMs.
Banks face relatively lower direct risks given lending is typically done on a senior secured basis and represents a modest portion of overall loan exposure. Partnerships between banks and non-banks have risen with the evolving regulatory landscape, which have provided banks with a source of risk transfer and enhanced capital efficiency.
We do not currently view private credit risks as systemic despite exhibiting various “bubble-like” attributes including rapid growth, financial innovation, spread compression, heightened competition, growing retail participation and rising borrower leverage. Nevertheless, private credit warrants continued close monitoring and would benefit from increased transparency to gauge risks and resilience of the evolving sector.




Latest news

US leveraged loans returns turn negative in October
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) has returned -0.26% this month through October 21, reducing its year-to-date return…

M&A activity begins to tick upward
In the third quarter of 2026, acquisition-linked loan volume across North America and Europe reached about $47 billion, up from $30.6 billion in Q2 and $29.5 billion a year ago.
