


Click here to learn more.
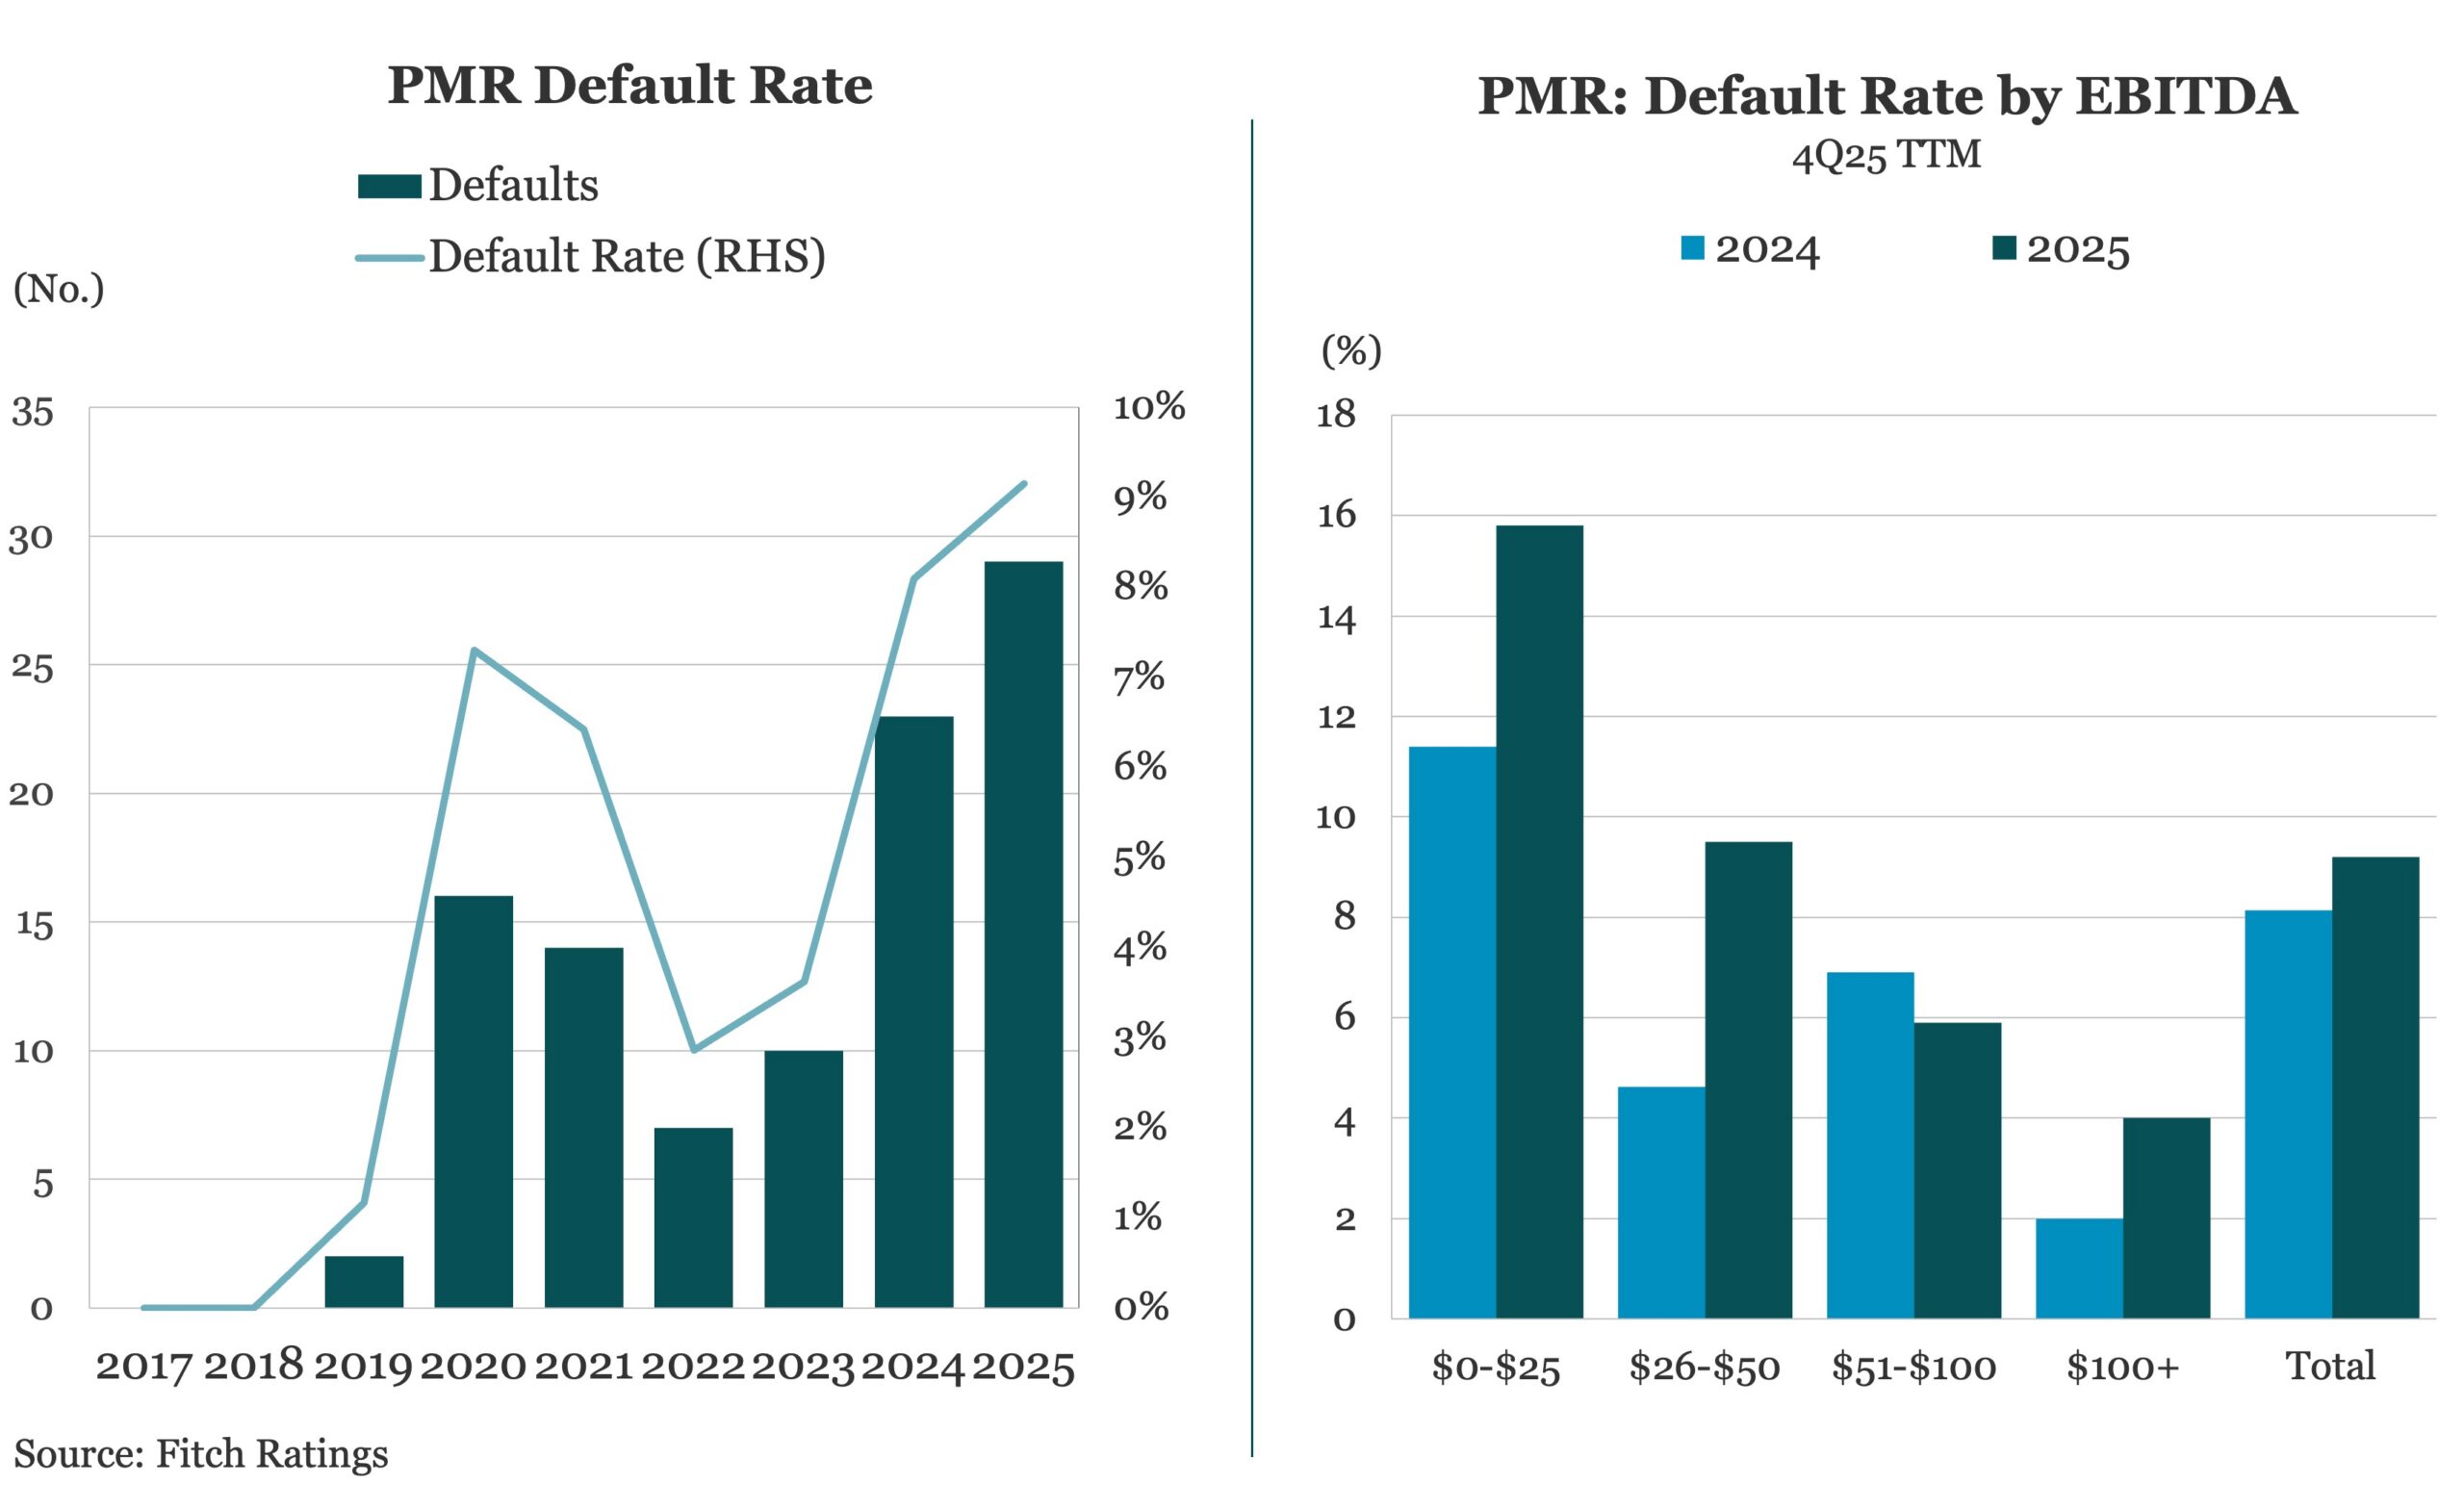
The default rate in Fitch Ratings’ privately monitored ratings (PMR) portfolio hit 9.2% in 2025, a new high, up significantly from 8.1% in 2024. Defaults were not concentrated in any particular sector, though Fitch recorded four defaults in the consumer products sector and three defaults among healthcare roll-ups. The PMR default rate is issuer-weighted and includes only unique defaulters.
Smaller issuers defaulted at a higher rate than larger issuers for the second year that Fitch has been tracking the data. Issuers with $25 million or less of EBITDA defaulted at a rate of 15.8% in 2025, while issuers with more than $100 million of EBITDA had a default rate of only 4%.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…