


Click here to download report.
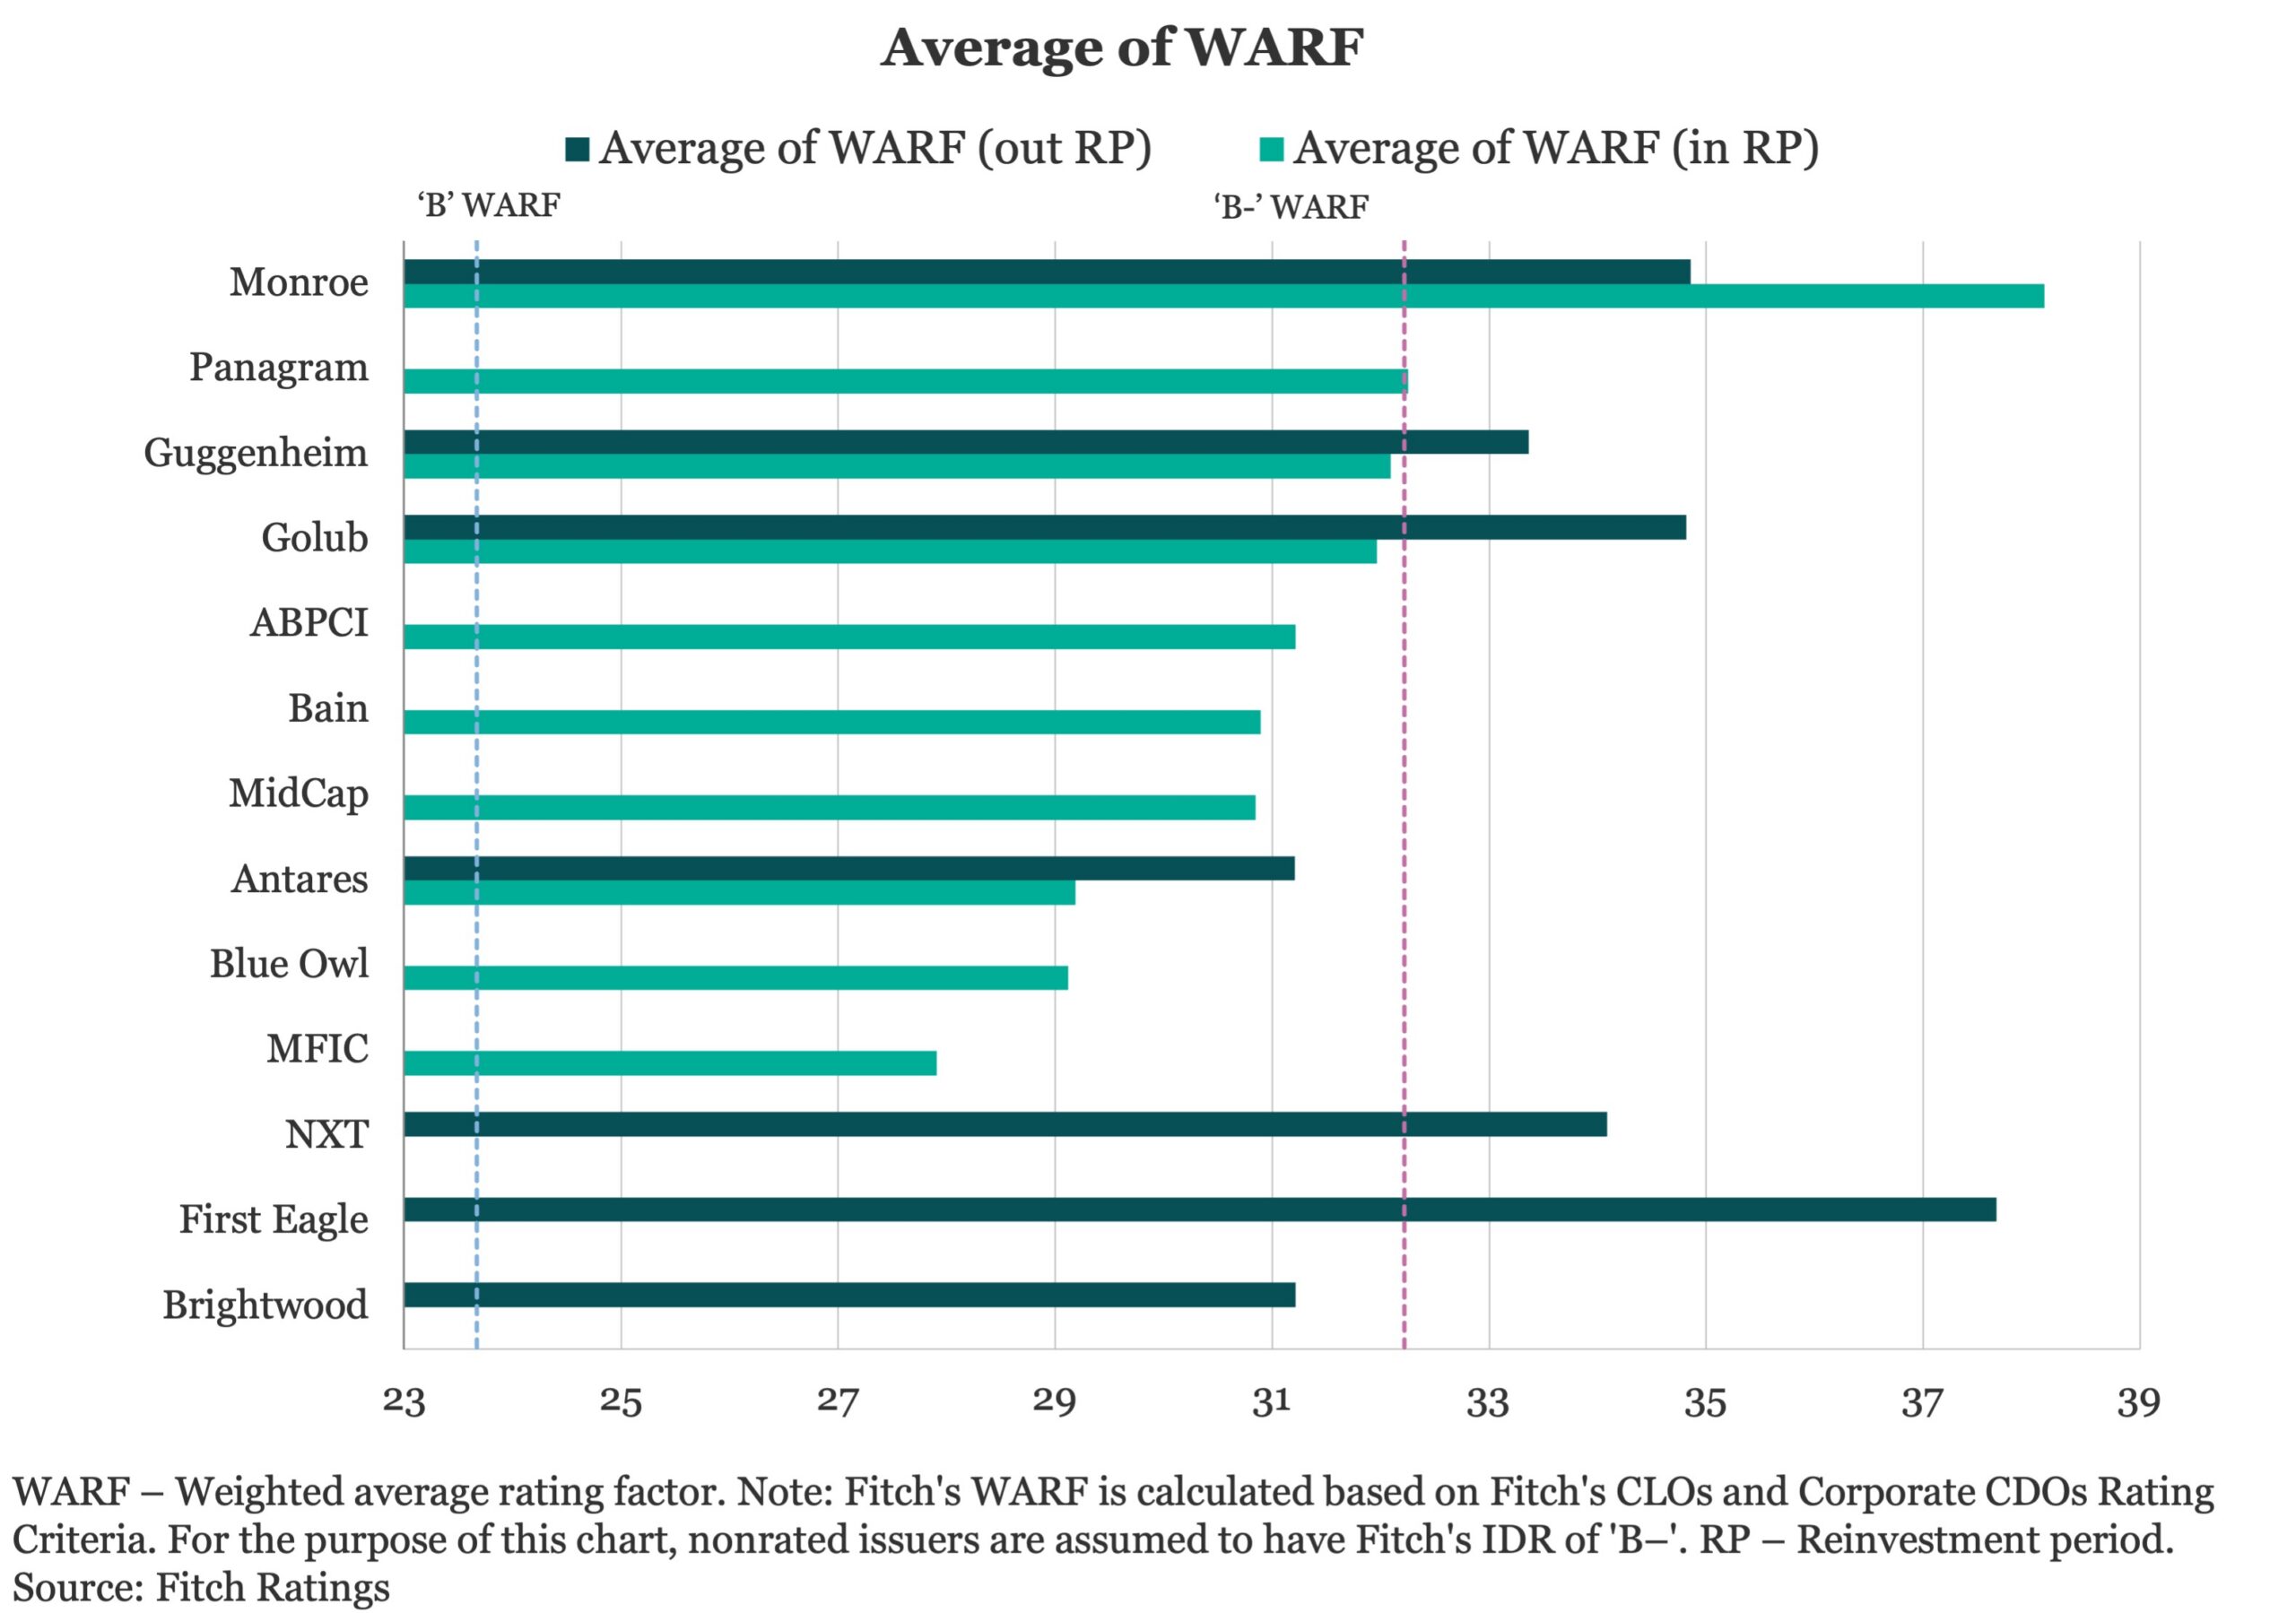
All Fitch-rated MM CLOs include a Fitch Test Matrix as part of a CLO’s Collateral Quality Tests (CQTs) in MM CLOs, including Fitch weighted average recovery rate (WARR), Fitch weighted average rating factor (WARF), weighted average spread (WAS) and weighted average life (WAL), generally remain in compliance against test limits for deals in reinvestment. The median cushion to limits were 1.9% for WARR, 2.0 points WARF, 0.3% WAS and 2.4 years WAL. One MM CLO in reinvestment is not in compliance with both the Fitch WARR and WARF test limits at the end of August 2024.



Latest news

US Leveraged Loans Return 3.36% to Investors YTD
The Bloomberg US Leveraged Loan Index (Ticker: LOAN) returned 0.96% in August and has gained an additional 0.28% through September…

PE dry powder
The capital that is being raised is flowing overwhelmingly to the largest, most established managers.

Middle market debt held by BDCs vs High yield vs Treasury yields
The blue line represents the current dividend yield of the VanEck BDC Income ETF (BIZD), which stood at 11.7% as…